
Forex Major Currencies Outlook (Oct 12 – Oct 16, 2026)
Week Ahead Summary
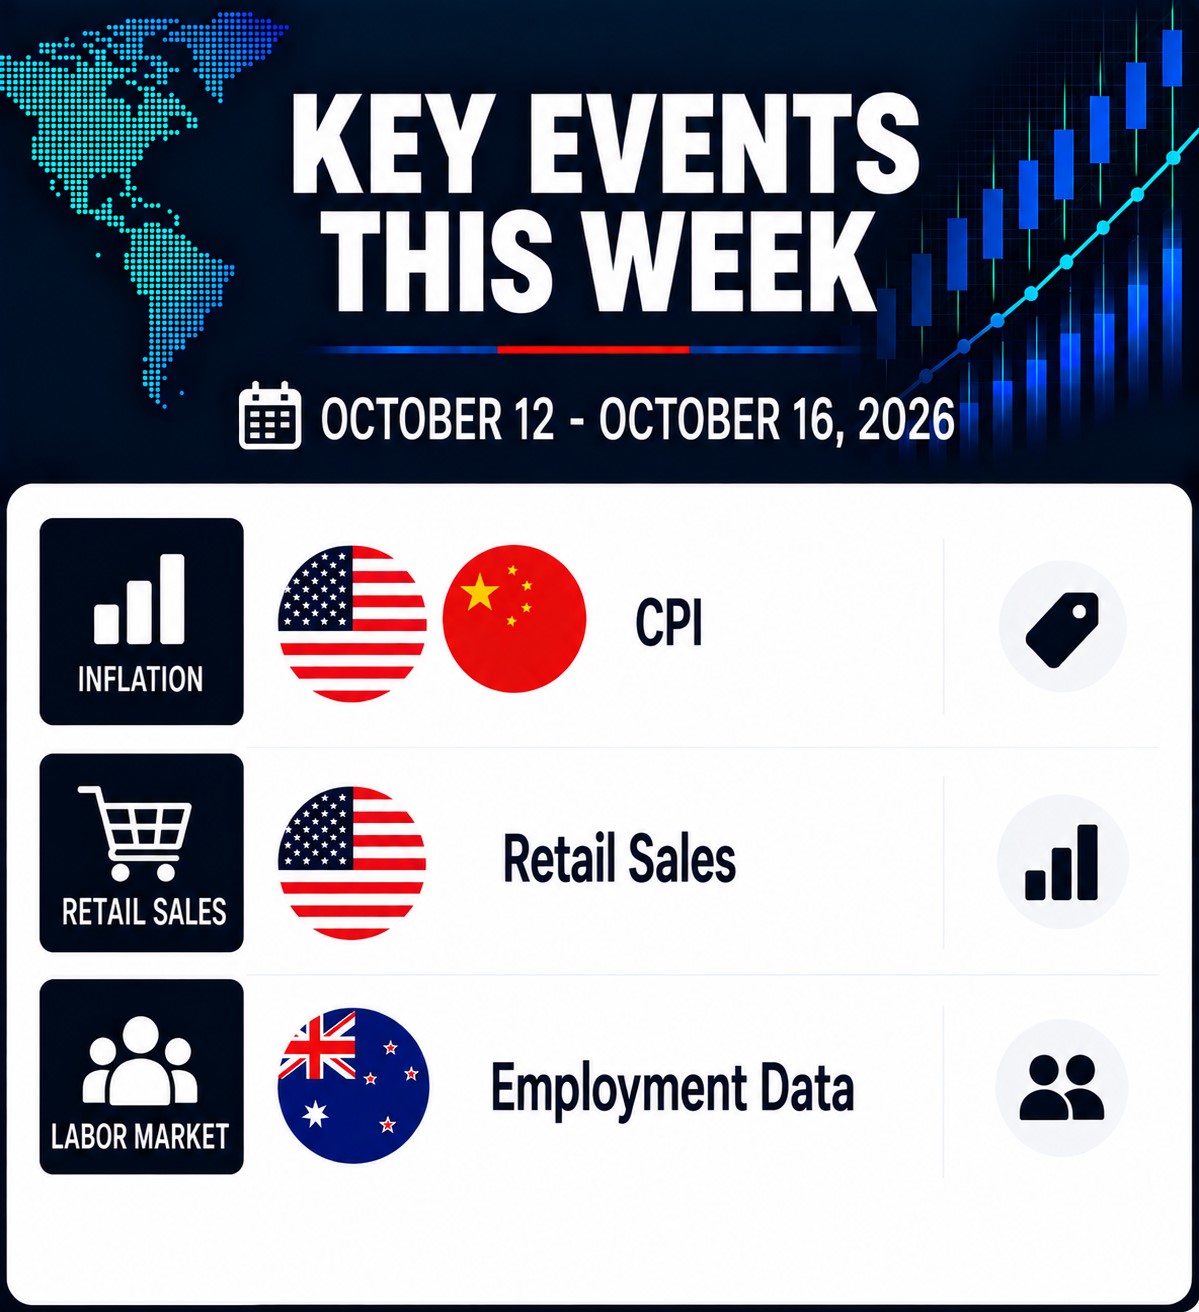
Inflation data from the US and China as well as retail sales from the US and employment data from Australia will highlight the week ahead of us.
USD — US Dollar
First round of elections in Brazil saw Flavio Bolsonaro gained 47% of the votes while President Lula gained 45%. The second round will be held on October 25 and markets think that votes will lean Bolsonaro’s way. Bolsonaro is calling for fiscal austerity and deregulation which led to currency and bond market rally.
US ISM services PMI for the month of September eased to 54.9 from 55.4 in August. The reading still stays deep in expansion territory. The report shows slower growth in business activity and new orders, both still around 60 while new export orders plunged into contraction. Employment index, on the other hand, managed to return to expansion as it printed 50.1 and we get stronger backlog of orders indicating improvement in future new orders. Prices paid rose to a new high of 74 as inflationary pressures keep mounting and are not letting go.
FOMC minutes from the September meeting presented a hawkish message. The decision to raise rates was unanimous and majority of participants sees another rate hike by the end of the year as appropriate. They see labour market risks as diminishing and broadly based while inflation risks are skewed to the upside. Several members see current policy rate as not restrictive enough. Members also expressed their surprise about the pace and magnitude of AI investments. They see it as additional inflationary push.
The yield on a 10y Treasury started the week at 5.25%, rose to 5.35% and finished the week at around 5.24%. The yield on 2y Treasury started the week at 4.79%, rose to 4.84% and finished the week at around 4.80%. Spread between 2y and 10y Treasuries started the week at 46bp and finished the week at 44bp. After weak NFP report FedWatchTool sees the probability of a no change at a September meeting at around 80% while probability of a 25bp rate hike is at around 20%. S&P 500 and NASDAQ both reached new ATH during the week.
This week we will have September inflation and retail sales data. Headline CPI is expected to increase while core is expected to stay unchanged.
Important news for USD:
Wednesday:
-
CPI
Thursday:
-
Retail Sales
EUR — Euro
September final services and composite were unchanged at 53 and 53.1 respectively. Growth was seen in both sectors which is encouraging but price pressures are increasing from both sides, input costs and output prices, creating strong inflationary pressures and causing troubles for the ECB.
Spanish Prime Minister Pedro Sanchez called for snap elections to be held on November 29. French OAT spreads were widening on the back of political turmoil in France and now there is potentially another political crisis brewing in the Eurozone. Marine Le Pen has pledged to reduce the budget deficit to 3.7% of GDP next year and reduce public spending to below 50% of GDP by 2032 which managed to lower OAT-Bund spread. Analysts are skeptical about her proposal as it rests more on ambitious spending cuts rather than on solid program. One point that is very enticing for the markets is the proposal of constitutional “golden rule”. Referendum is needed for it to be implemented but if it is approved it would require deficit to remain below the level needed to stabilize debt-to-GDP level to required 60%.
GBP — British Pound
Final reading of September services saw it revised up to 52.1 from 51.7 as preliminary reported thus showing smaller decline from 52.5 in August. The report shows that output continues to grow but that growth is slowing down. On the other hand, input prices are rising at a fast tempo due to the surging fuel prices which in turn dampens the business optimism. Composite was also revised higher and now shows a 52 print compared to 51.7 as preliminary reported and down from 52.5 the previous month.
BoE MPC member Megan Greene warned that it is likely that second-round effects from current inflation cycle will appear and added that high wage growth is a concern as she sees a potential for a wage-price spiral. Greene is one of the most hawkish members and her comments are in line with her hawkish views. BoE Governor Bailey, a neutral, stated that monetary policy needs to show “unwavering” commitment to returning inflation to target.
AUD — Australian Dollar
Aussie had a quiet week without any notable news and its movements were influenced by market forces. It managed to gain some ground against EUR, GBP and JPY but against other currencies it spent the week within a tight range.
This week we will have inflation and trade balance data from China as well as employment data from Australia.
Important news for AUD:
Wednesday:
-
CPI (China)
-
Trade Balance (China)
Thursday:
-
Employment Change
-
Unemployment Rate
NZD — New Zealand Dollar
First dairy auction in the month of October saw prices rise 1.2% after falling 1.1% in second auction of September. The biggest gain was in Skim Milk Powder while the biggest drop was in Lactose prices. Kiwi seems to be founding bottom as it gained against all of the majors.
CAD — Canadian Dollar
September employment report showed abysmal figures. The economy lost 68.3k jobs, after losing 41.7k jobs in August, while expectations were for it to add 9.2k jobs. The unemployment rate ticked higher to 6.5% while participation dropped to 64.8% form 65%. Both full-time and part-time employment lost jobs with former posting more than 35k job loses (35.4k) for the second month in a row while former showed job loses of 32.9k. One bright point in the report, due to lower participation rate most likely, is that wages rose 2.3% y/y compared to 2% y/y the previous month. The report shows effects of Trump tariffs and BoC will stay on hold at their next meeting after such weak employment report.
JPY — Japanese Yen
Final services PMI for the month of September was revised down to 51.3 from 51.6 as preliminary reported and down from 52.5 in August. The report shows that Kumamoto earthquake had caused some slowdown in activity as was evident in slowing of growth in new orders. At the same time, new export orders plunged. The rise in input costs eased while output prices increase accelerated indicating that companies are passing rising costs directly to consumers. Employment was a bright spot in this report as it surged at a fastest pace in seven months. Composite printed 52.3, down from 53.5 the previous month.
BoJ Governor Ueda spoke in Tokyo and stated that underlying inflation is approaching 2% target. He added that despite September rate hike financial conditions remain accommodative and are helping support economic recovery. Ueda stated that further rate hikes will depend on likelihood of materializing of their baseline projections. Hawkish comments from Ueda, especially on underlying inflation but they do not cement October rate hike. December meeting is more likely to deliver another rate hike. Additionally, average wages rose by 3.8% y/y in August while real wages rose 1.5% y/y making it eighth consecutive monthly wage increases thus adding to pressures on BoJ to deliver rate hikes. Despite real wages steadily rising household consumption continues to decline as shown by August drop of 3.1% y/y making it nine consecutive months of declines in consumption.
CHF — Swiss Franc
SNB total sight deposits for the week ending October 2 came in at CHF464.2bn vs CHF456.8bn the previous week. This is the fourth consecutive week of rising deposits as SNB is forced to fight Swissy strength caused by French debt crisis. Seasonally adjusted unemployment rate stayed at 3.1% in August for the fourth month in a row.
You can follow all economic events on the Economic Calendar page on our Website. MT server time is set to GMT+3 and if you need assistance converting MT server time to your local time you can use some of the online time converters such as WorldTimeBuddy.
Please note that this analysis should not be used as investing advice as it is only an overview of the economic events influencing the markets. Please remember that our accounts have Market Execution. Please note how Execution works during high impact news and other times of low liquidity.