
Forex Major Currencies Outlook (Nov 16 – Nov 20, 2026)
Week Ahead Summary
Forex Major Currencies Outlook (Nov 16 – Nov 20, 2026)
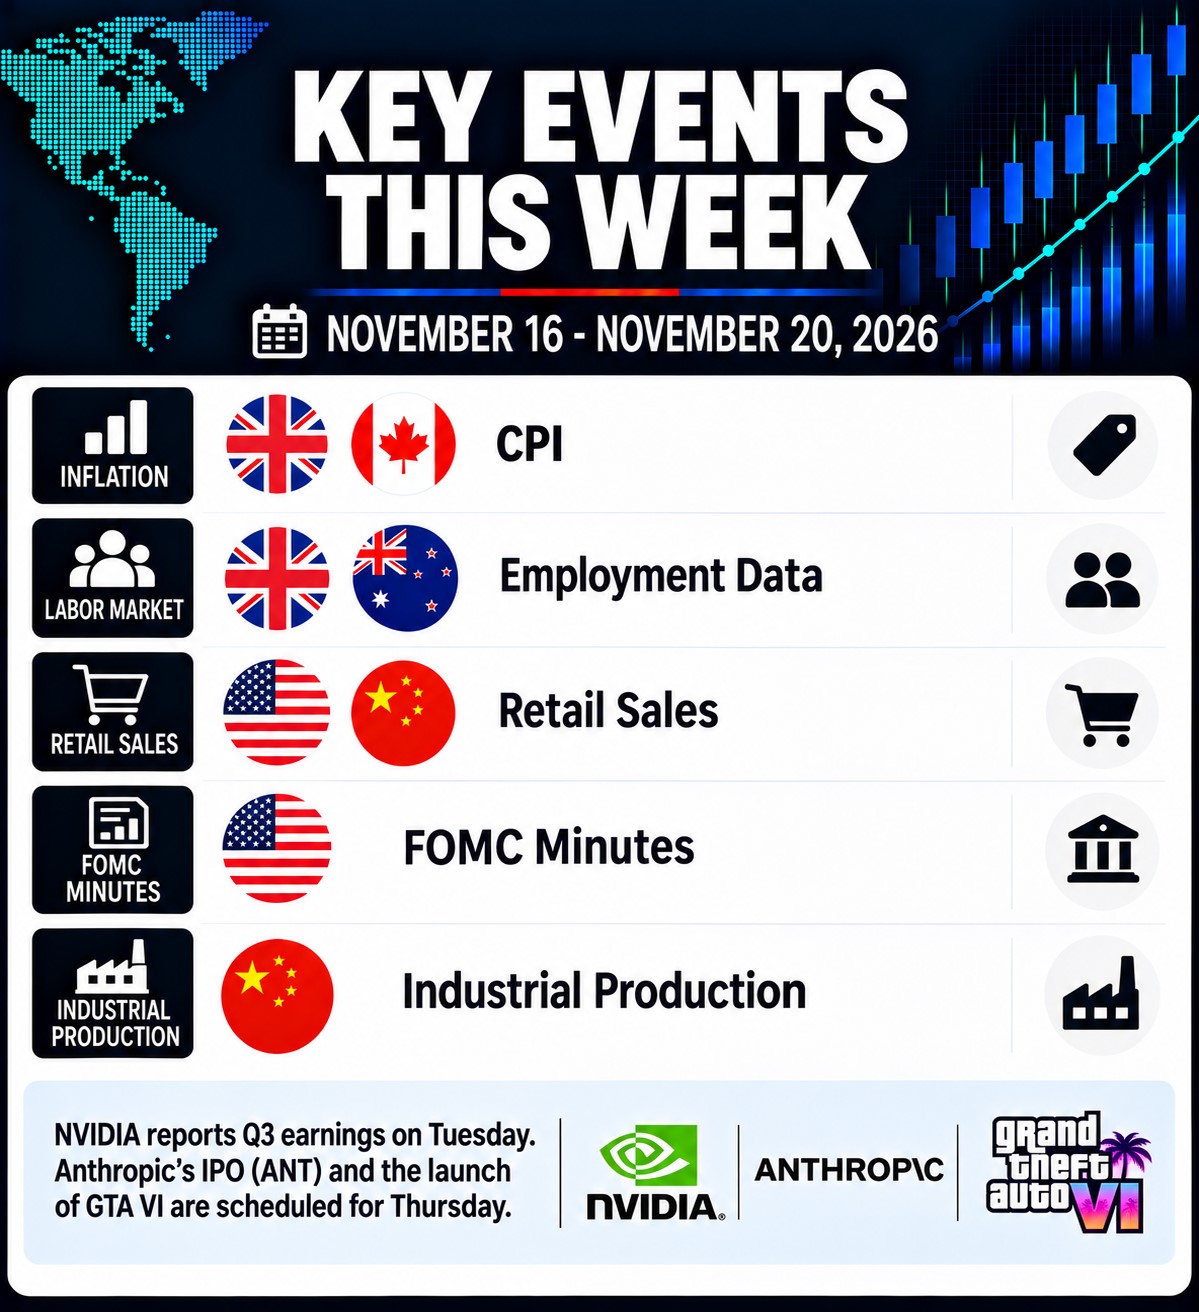
Inflation data from the UK and Canada, employment data from the UK and Australia, retail sales from the US and China, FOMC minutes, as well as industrial production data from China will highlight busy week ahead of us. Additionally, we will have NVIDIA earnings report on Tuesday as well as Anthropic IPO (ANT on NASDAQ) and GTA VI release on Thursday.
USD — US Dollar
NVIDIA CEO Jensen Huang admitted having an affair with a woman who is accused of being a Chinese spy. The investigation into whether Huang was led into a honeypot, where a foreign operative tried to gather sensitive information from him, is ongoing. Later during the week it was announced that he will step down from his CEO position leaving the board as well. Current CFO Colette Kress will take over until new CEO is found. NVIDIA reports earnings next week and their conference call will be a high impact event on November 17, President Trump declared that US is not in need of peace deal with Iran which was followed by strikes in Iran. Trump also threatened Cuba stating he would consider a week-long campaign there.
Fed Governor Waller put out a strong hawkish remarks as he stated that if core CPI comes above expected 0.3% m/m Fed may need to hike by a 50bp. He added that even if inflation improves he is endorsing a 25bp December rate hike stating that inflation is too high and that September inflation print was bad. Waller clarified that he is particularly worried about the breadth of price increases.
October inflation report saw core CPI come in at 0.3% m/m (0.296% undrounded) vs 0.2% m/m as expected but not higher than the level Waller warned about. Shelter, the largest component accounting for almost a third of the overall index, rose 0.3% m/m. Used cars showed the biggest decline with prices falling 1.2% m/m. Headline number rose 0.4% m/m (0.35% unrounded) vs 0.3% m/m as expected pushed higher by the high energy costs. Supercore rose 0.289% m/m. There are no yearly figures as last October there was no inflation report published due to government shutdown. Stronger than expected numbers make December hike fully priced in, the only question is whether it will be a 25bp rate hike or a 50bp rate hike.
The yield on a 10y Treasury started the week at 4.87%, started to rise after Governor Waller comments, rose to 5.16% and finished the week at around 5.15%. The yield on 2y Treasury started the week at 4.52%, surged after the Governor Waller comments about being open for a 50bp rate hike, rose to 4.90% and finished the week at around 4.88%. Spread between 2y and 10y Treasuries started the week at 33bp and finished the week at 27bp. FedWatchTool sees the probability of a 25bp rate hike at the December meeting at around 88% while a probability of a 50bp rate hike is seen at around 12%.
This week we will have retail sales data, expected to show further growth and strength of US consumer as well as minutes from the October FOMC meeting.
Important news for USD:
Tuesday:
-
Retail Sales
Wednesday:
-
FOMC Minutes
EUR — Euro
Final inflation reading for the month of October saw German print confirmed at 2.8% y/y for headline CPI and 2.1% y/y for core CPI. Both prints are down from 3.3% y/y and 2.4% y/y respectively. Energy prices are still keeping inflation high but with core inflation coming down it shows that inflationary pressures are not broad and that will provide some comfort for ECB. French reading was confirmed at 3.4% y/y, up from 3.1% y/y in September due to surging energy prices, but unlike in Germany, in France core CPI rose to 1.7% y/y from 1.5% y/y the previous month on the back of rising services inflation. Spanish reading was confirmed at a very high level of 4.9% y/y, second month in a row, for headline and 3.1% y/y for core CPI. Second estimate of Q3 GDP was unchanged showing growth of 0.4% q/q and 1.3% y/y.
GBP — British Pound
Q3 GDP came in line with expectations showing growth of 0.7% q/q and 1.9% y/y. Services contributed with 0.9% growth, production with 0.1% while construction declined 0.7%. Real household consumption and government consumption both rose 0.6% q/q thus growing stronger than 0.3% q/q and -0.5% q/q respectively in previous quarter. Business investment growth slowed down to 0.4% q/q with net exports being drag on the reading. BoE MPC member Megan Greene stated that proactive tightening is appropriate to insure against wage risks. Deputy Governor Claire Lombardelli added that a December 25bp rate hike remains plausible but that it will depend a lot on the developments in the Middle East. She has warned that energy shock became persistent and is raising the chances of second-round effects.
This week we will have employment and inflation data.
Important news for GBP:
Tuesday:
-
Payrolls Change
-
Unemployment Rate
Wednesday:
-
CPI
AUD — Australian Dollar
Chinese CPI declined in October to 0.7% y/y from 0.9% y/y in September while markets were expecting a 0.8% y/y print. Declines in food prices, vegetable prices particularly, dragged the reading down. Core print also declined printing 0.8% y/y, down from 1% y/y the previous month. PPI continued to increase rising 5.7% y/y vs 5% y/y in September and more than 5.3% y/y expected as prices related to mining and excavation surged. October trade balance showed yet another $100bn+ surplus and confirmed that total surplus for the first 10 months of 2026 exceeded $1tln. This is the second year in a row that trade surplus crossed $1tln in a year and it happened one month faster than previous year as surplus reached that level in November of 2025.
This week we will have employment data from Australia and economic activity data from China.
Important news for AUD:
Monday:
-
Industrial Production (China)
-
Retail Sales (China)
Thursday:
-
Employment Change
-
Unemployment Rate
NZD — New Zealand Dollar
Parliamentary elections saw Prime Minister Luxon and his National-led coalition win 67 out of 131 votes thus having a very thin majority. There is almost 400k votes from New Zealanders living abroad to be counted and they can easily swing the vote. Final results will be published on November 27 and by then the country will be in “political limbo” which will increase volatility in the currency. National coalition removes the risk that the RBNZ will be forced back to a dual mandate.
CAD — Canadian Dollar
Final manufacturing sales for the month of September came in flat while August reading was revised up to show a 1.8% m/m growth. Final wholesale trade showed 0.7% m/m growth while previous month’s reading was revised to show a smaller 1.4% m/m decline. CAD has started a week on the wrong foot only to benefit from USD strength later in the week and finish the week unchanged against the majors.
This week we will have inflation data where a further tick up is expected.
Important news for CAD:
Monday:
- CPI
JPY — Japanese Yen
BoJ Governor Ueda reiterated his stance that underlying inflation should stay around targeted 2% but warned that there are upside risks, mainly from high energy prices. He added that wage growth is consistent with 2% inflation. September household spending plunged 6.8% y/y making it tenth consecutive month of declining consumption. Last week we had real wages data showing them increase for the ninth straight month and despite that consumers still refrain from spending. Tankan business sentiment index showed a new five-year high for manufacturing sector as Japan is one of the most important supplier of goods for AI data center build-out. PPI, corporate goods price index, for the month of October jumped to 7.1% y/y from 6.8% y/y in September thus beating expectations for a drop to 6.5% y/y on the back of higher energy and raw material prices. This data point pushes chances of a December hike higher. USDJPY was hovering near the 160 level and there was some tough talk from Prime Minister Takaichi.
This week we will have preliminary Q3 GDP reading.
Important news for JPY:
Monday:
-
GDP
CHF — Swiss Franc
SNB total sight deposits for the week ending November 6 came in at CHF452.9bn vs CHF455.8bn the previous week. This is the lowest level of deposits in eight weeks and Swissy had a strong week as a result of it.
This week we will have preliminary Q3 GDP reading.
Important news for CHF:
Monday:
-
GDP
You can follow all economic events on the Economic Calendar page on our Website. MT server time is set to GMT+2 and if you need assistance converting MT server time to your local time you can use some of the online time converters such as WorldTimeBuddy.
Please note that this analysis should not be used as investing advice as it is only an overview of the economic events influencing the markets. Please remember that our accounts have Market Execution. Please note how Execution works during high impact news and other times of low liquidity.